
The MiCA Crypto Alliance Hosts “Ready for the UK’s Cryptoasset Regime” in London
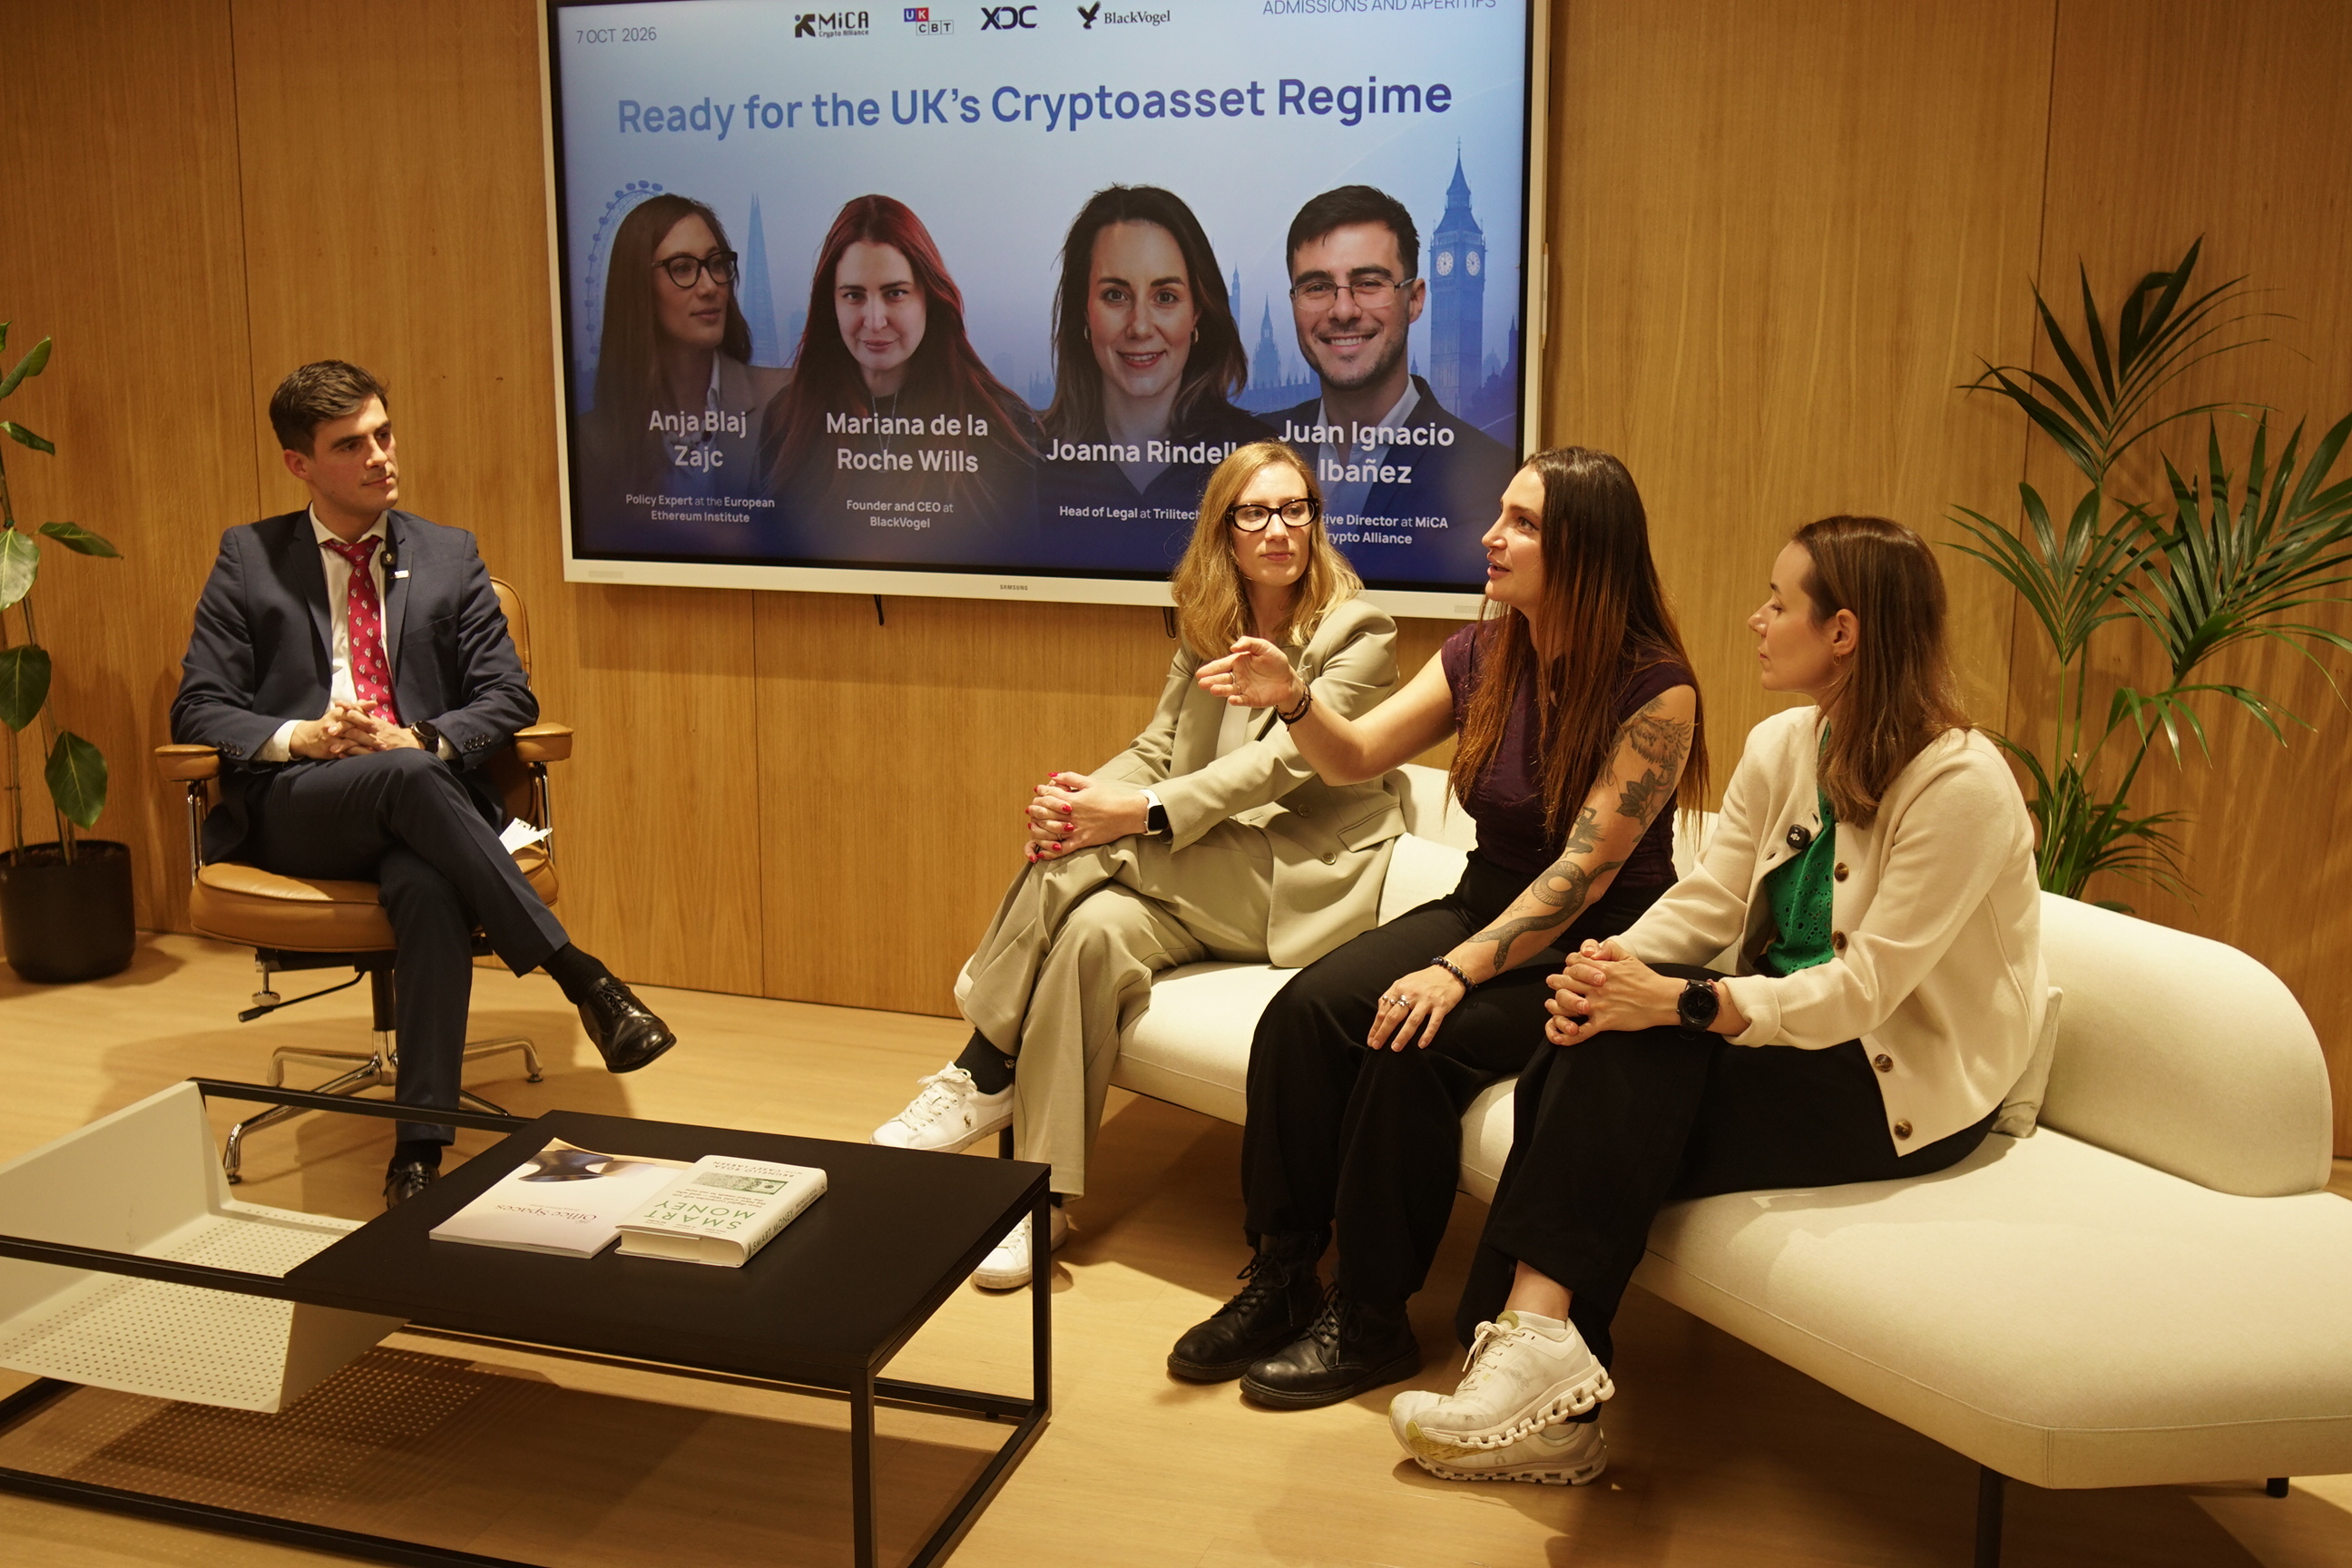
On 7 October, the MiCA Crypto Alliance hosted “Ready for the UK’s Cryptoasset Regime: Admissions & Aperitifs”, a Digital Assets Week side event at the XDC Network’s London office. Token issuers, trading platform operators and compliance practitioners came together to look at how the UK’s new admission requirements will work in practice.
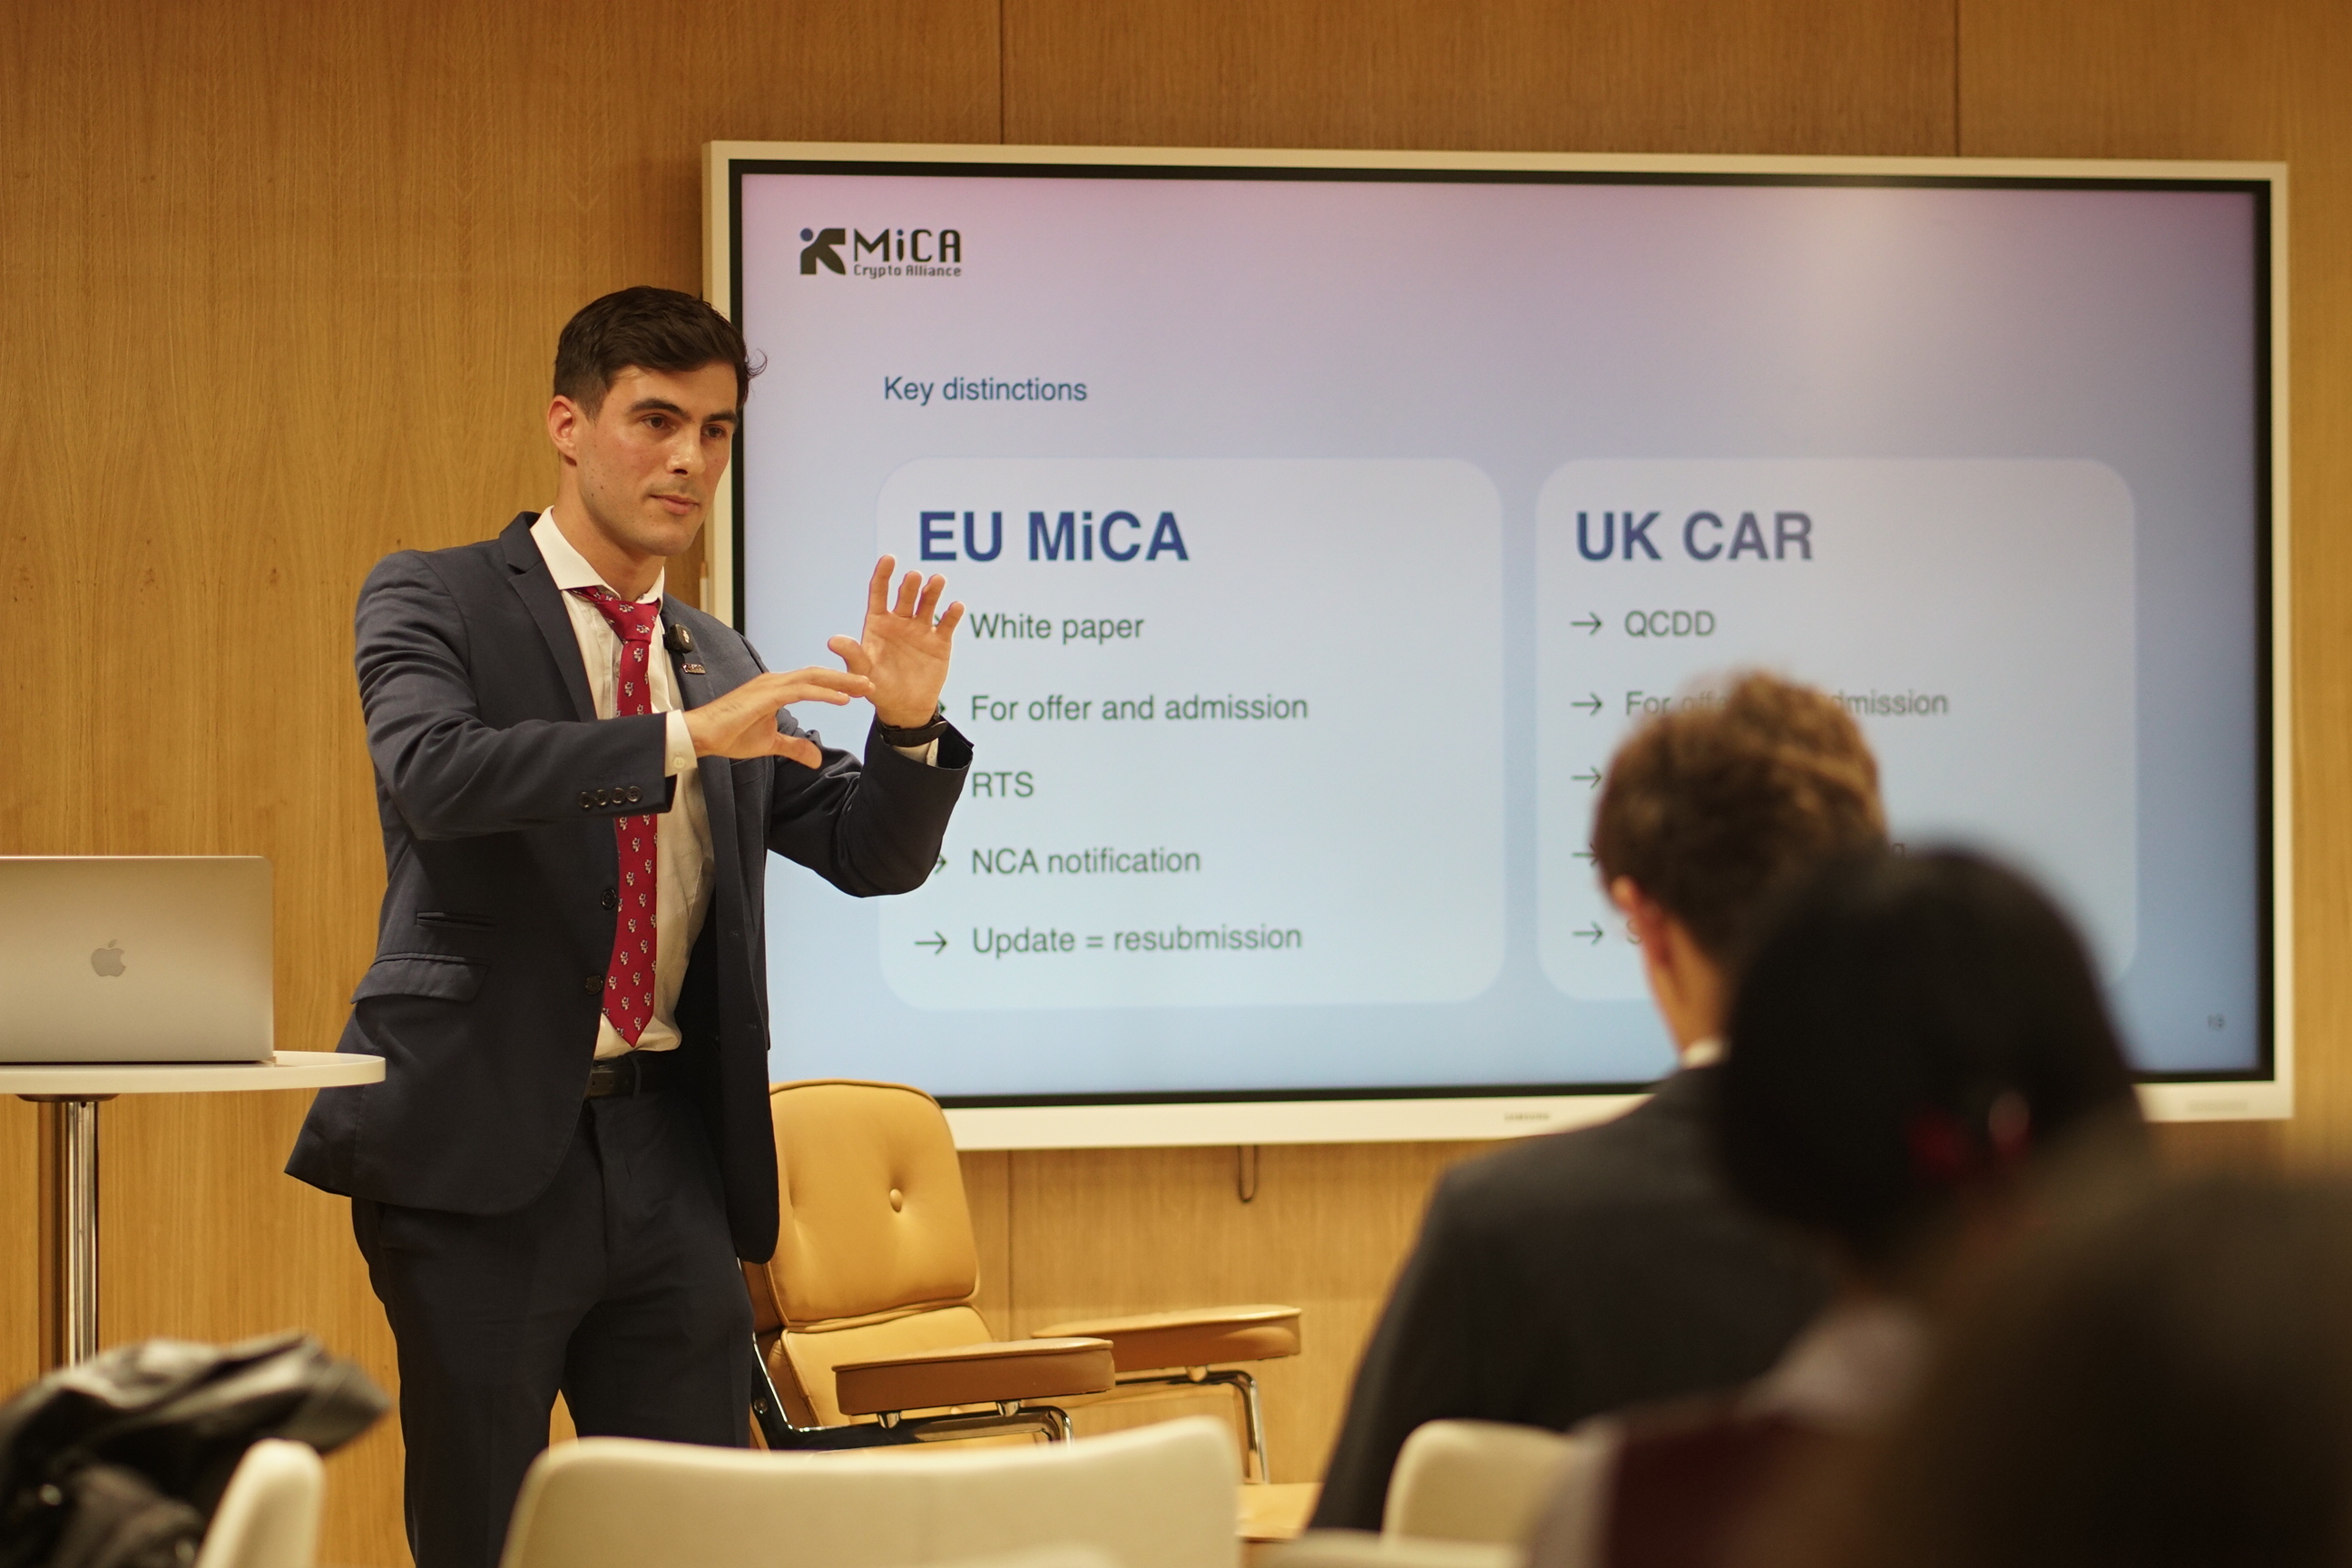
Juan Ignacio Ibañez, our Executive Director, opened with a presentation, followed by a panel discussion and questions from the room. The event ran under the Chatham House Rule, so the takeaways are not attributed to individual participants.
The QCDD: the UK’s answer to the white paper
What is the UK counterpart to the MiCA white paper? It is the Qualifying Cryptoasset Disclosure Document, or QCDD. It does the same job: it gives investors a standard set of information when a cryptoasset is admitted to trading.
The two regimes get there differently. MiCA works through a single regulation with standardised white paper rules. The UK combines the Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026, FCA rules and the rulebooks of individual trading platforms. A project seeking admission to several UK venues may therefore need to meet a different set of requirements at each one. We are mapping those requirements and will publish the results.
Who receives the document, and what happens when things change
For non-stablecoin admissions, the QCDD goes to the trading platform, which reviews and publishes it. Under MiCA, the white paper is notified to the national competent authority. Stablecoin QCDDs sit under a separate FCA framework, with a central repository kept by the FCA.
Updates work differently too. The UK framework allows a supplementary disclosure document to deal with material changes or corrections, so the original stays in place. MiCA Article 12 requires the white paper itself to be modified when there is a significant new factor, a material mistake or a material inaccuracy. Which model serves issuers and investors better was part of the discussion.
Rules and principles, converging
MiCA is built on rules and the UK regime on principles. On disclosure, they share more than they differ. The same logic is spreading beyond Europe. The SEC’s proposed Regulation Crypto Assets includes proposed disclosure principles, and Bermuda and Brazil have comparable frameworks. The US proposal sits in a different securities-law setting and is not a direct equivalent of a QCDD or a MiCA white paper.
Will international convergence take hold, or will regional silos persist? Perspectives on the panel varied. The risk is fragmentation for globally traded assets. The opportunity is industry-led convergence and, in time, regulatory interoperability.
Is the UK regime competitive?
The panel’s assessment was broadly constructive, with qualifications. The UK can learn from MiCA’s implementation, which is a second-mover advantage. A single regulator may also bring more operational coherence than the decentralised supervision of the EU, and London’s legal and compliance infrastructure adds to the case. The burden falls unevenly. Large exchanges already authorised under MiCA or similar regimes face a small incremental cost. Newer and smaller entrants face a heavier one.
Perimeter questions MiCA left open
Staking, lending, borrowing, perpetuals and prediction markets were left out of MiCA or left unclear, and the targeted review now asks whether to extend the perimeter. Industry views have shifted. Some who once urged exclusion now ask for regulation, because clarity makes institutional participation possible. Others still resist.
Staking drew the most discussion. Pooled structures can raise collective-investment or alternative investment fund questions, especially where pooling combines with meaningful operator discretion and tradeable secondary instruments. The UK technical-services exclusion in Article 9Z9 covers providers that enable others to stake, for example by running a validator node, without presenting themselves as offering staking to the public. Its boundaries need more definitional work.
What issuers and platforms should do now
Whichever way convergence resolves, token issuers, offerors and trading platforms need to consider the UK’s disclosure requirements now. That is why we have launched our services for QCDDs and SDDs. Practitioners should also check any AI-generated summary of this new terminology against the primary legislation.
We thank our panellists, the UK Centre for Blockchain Technologies for its involvement, the XDC Network for the space, and all our guests.